

Skrill - Fast, secure payments
by Paysafe Holdings UK Limited
4.5
- Safety
- 100% Safe
- Category
- Finance
- Ratings
- 4.5
- Price
- Free
- Download
- 10.00M
This app is secure, reliable, free to install, and offers fast downloads without any risks or malware.
Screenshots
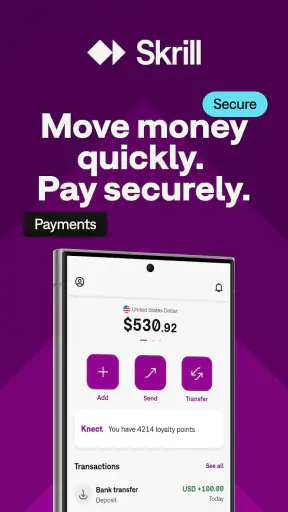
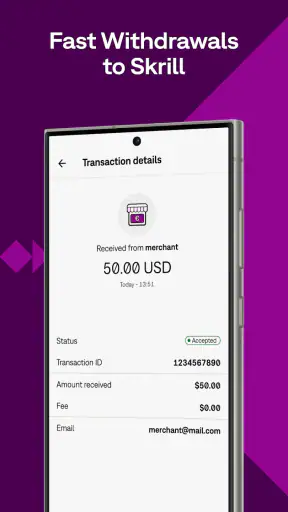
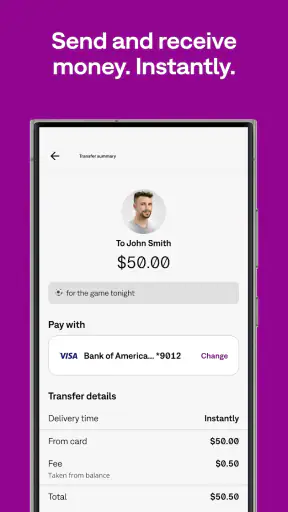
 Analysis by Getfullapps
I approached Skrill as a practical finance app rather than just another way to move money. Its purpose is straightforward: it lets you transfer money using your phone, and that can be useful when you want a separate digital payment account instead of relying only on a bank app or a card. My experience was generally positive, but the smoothest results came from treating setup and account checks as part of the process, not as minor details to rush through.
That distinction matters because payment apps are judged less by how attractive they look and more by what happens when a transfer is delayed, a sign-in fails, or a transaction needs attention. Skrill is free to download and aimed at everyone, with Paysafe Holdings UK Limited behind it. It has been available since September 2014, and its current Android version is 3.191.0-2026081013, requiring Android 8.0 or later. Those details make it a well-established option, but they do not remove the need to check that your phone, account details, and payment method are all ready before you depend on it.
Where people usually get stuck with Skrill
The first point of friction is often not the transfer itself. It is getting the account into a state where the app can be used confidently. A new user may expect to install the app, enter a few details, and immediately send money. In practice, financial services commonly need accurate personal information and may ask for additional checks before certain actions work. I found it sensible to use my real details from the beginning and to avoid creating an account in a hurry while travelling, using an unfamiliar connection, or switching repeatedly between devices.
Another common stumbling block is confusing the app with a traditional bank account. Skrill is a digital wallet and payment service, so the way money arrives, sits in the account, and leaves it may not match the workflow of your bank. Before sending anything, I would confirm whether the recipient expects money through Skrill specifically and whether the intended route is a wallet transfer or another available payment method. A surprising number of failed attempts begin with the sender and recipient imagining different kinds of transaction.
Sign-in trouble can also look like a payment problem. If the app opens but an action will not continue, I first separate the questions: can I access the account, can I see the balance, and can I complete the particular transaction? That simple order prevents unnecessary retries. Repeatedly tapping a payment button or reinstalling immediately can make the situation harder to understand, especially when the real issue is an account check, a connection interruption, or a temporary service response.
The most useful habit is to identify the exact stage that failed. Is the problem logging in, adding money, choosing a recipient, confirming the transfer, or waiting for the result? Skrill is easier to troubleshoot when those stages are treated separately. A vague “it does not work” is frustrating, while “the account opens but confirmation does not complete” gives you a much clearer next step.
Why a transfer can feel slower than expected
A phone-based transfer feels instant because the request is made with a few taps. That does not mean every part of the transaction is instant. The app may need to communicate with the payment method, apply account checks, or wait for the other side of the transaction to respond. I avoid promising a recipient that money has arrived until I can see a completed result in the app and the recipient confirms it independently.
Articles to Explore Next

Uber Eats Makes Dinner Easier to Manage, but the Fees Add Up

Google Photos Turns a Camera Roll Into a Library You Can Find Your Way Through

Canva on Mobile: Adopt It for Quick Visuals, Test It for Demanding Work

Google Drive Keeps Work Moving Until It Doesn’t

Switching to Weather - By Xiaomi Means Relearning Your Forecast Routine

Ludo King and the Social Life of a Lucky Six
This is especially important when the transfer is time-sensitive. For rent, a bill, or a purchase that cannot be delayed, I would not make Skrill the only route unless I had already used the same workflow successfully. A bank transfer may be the better choice when the recipient needs a conventional account transaction, while a card may be more convenient for a normal checkout. Skrill is most convincing when both sides understand the service and the sender has time to check the result.
Setup checks that prevent avoidable trouble
Before using the wallet for an important payment, I recommend a short preparation routine. Install the latest available version for your device, make sure Android meets the minimum requirement, and use a stable connection. Then check that the account information is entered consistently. Small differences in names, addresses, or contact details can create confusion later, particularly if the service asks you to confirm who you are.
I would also keep access to the email address or phone details associated with the account. Losing access to those channels can turn a simple sign-in issue into a longer recovery process. This is not unique to Skrill, but it is more important in a finance app than in a casual social application. I would never share a sign-in code or approve an unexpected request merely because it appears urgent.
A useful setup check is to decide what the app is for before adding money. If the goal is receiving money from another person, agree on the recipient details first. If the goal is paying online, confirm that the merchant or service accepts Skrill. If the goal is moving money between your own accounts, compare the steps and any applicable conditions with your usual bank method. This planning avoids putting funds into a wallet before knowing how they will be used.
The app is free, but “free” should not be read as “every possible transaction is costless.” Payment services can apply different conditions depending on the action, funding route, currency, or destination. I would inspect the final confirmation screen carefully rather than assuming that the amount entered is the only amount that matters. If the displayed total is not what I expect, I stop and investigate instead of confirming out of habit.
Making the first real transaction less stressful
For a first use, I prefer a small, non-urgent transaction with someone I trust. The aim is not to test the app with money I cannot afford to have delayed; it is to learn the sequence from opening the wallet to confirming the result. I take a screenshot or note of the confirmation details for my own records, without exposing private information. That makes it easier to compare what I sent with what the recipient received.
I also check the recipient carefully before confirming. A familiar name or profile image is not enough if several contacts look similar. Reading the details slowly is one of the simplest ways to avoid sending money to the wrong person. Once a transfer has been confirmed, correcting an error may be more complicated than preventing it.
For regular use, I keep the app’s role narrow and clear. I do not treat it as a place to experiment with unfamiliar payment requests, and I do not use it as a substitute for keeping proper records. A wallet can make payments convenient, but I still track important transfers, note who was paid, and retain confirmation information until the other person is satisfied.
Recovering when a workflow breaks
When something goes wrong, my first recovery step is to stop repeating the action. I check whether the balance changed, whether the transaction appears in the activity area, and whether I received a confirmation message. If the money has already left the account, attempting the same transfer again could create a duplicate. If nothing changed, I close and reopen the app, check the connection, and try once more only after confirming that the original attempt did not complete.
Updating the app can help when a problem is caused by an older build, but I would not uninstall immediately. Reinstallation may remove convenient local state and can force another sign-in, which is unhelpful if the original problem is account access. I prefer a calm sequence: verify the connection, restart the app, check for an update, and then review the account or transaction status. If the issue remains, I use the service’s official support route and describe the exact stage that failed.
When contacting support, useful information is more valuable than a long emotional explanation. I would include the type of action I attempted, the approximate time, the visible status, and whether the balance changed. I would not send a password, full security code, or unnecessary payment details. A clear description helps distinguish a pending transaction from a rejected one or a simple display problem.
One non-obvious but important rule is to avoid making several changes at once. If I change the connection, switch devices, reset access details, and retry the payment repeatedly, I lose the ability to tell which action helped. I make one reasonable change, check the result, and keep a note of what happened. That approach is slower for a few minutes but much faster than creating a confusing trail of retries.
When the app is not the cause
Not every failed payment originates inside Skrill. The recipient may have supplied incorrect details, the funding source may have declined the request, or the merchant may not support the chosen payment route. A weak mobile connection can interrupt a confirmation even when the account itself is fine. I therefore compare the app’s status with the recipient’s status before deciding that the wallet is broken.
There is also a difference between a technical error and a transaction that needs review. If the app opens normally but asks for more information, that is not the same as a crash. If a payment remains unresolved, I avoid guessing whether it will eventually complete. I check the visible transaction state and wait for clear confirmation or support guidance rather than sending a second payment just to feel that I have done something.
Device compatibility deserves attention too. Skrill supports Android 8.0 and newer, so an older phone may not be suitable. Even on a compatible device, limited storage, an outdated operating system, or aggressive battery management can interfere with app behavior. I would first test the app under normal conditions, with enough free space and a reliable connection, before blaming the payment service.
Security problems should be handled separately from ordinary troubleshooting. If I notice an unfamiliar transaction or receive a suspicious request, I do not try to resolve it by replying to the sender or sharing account information. I secure access through the official app or support channel and keep records of what I saw. Convenience is never a good reason to lower the standard I would use for a bank account.
How Skrill compares with familiar alternatives
Compared with a bank app, Skrill can feel more focused on digital wallet transfers and online payment use. A bank app is usually the natural choice when the recipient wants a conventional bank account, when direct account history matters, or when I am managing broader banking tasks. Skrill becomes more appealing when both people already use it and want a phone-centered payment route without making the wallet part of a full banking relationship.
Compared with paying directly by card, the wallet adds an extra layer. That layer can be useful if I want to keep a payment balance separate from my main bank account or use a service that supports Skrill. It can also be unnecessary. For a routine purchase at a familiar merchant, direct card payment may involve fewer steps. I would choose the wallet for a clear reason, not simply because it is another option on the screen.
Compared with other digital wallets, the deciding factor is usually compatibility with the people and services involved. A wallet is only convenient if the recipient can use the money in the way they need. I would ask whether the other person already has an account, whether they need a bank transfer instead, and whether the transaction conditions suit the amount and currency involved. The best app is not always the one with the most features; it is the one that creates the fewest mismatches in a particular payment.
Skrill’s scale gives it a reassuring level of familiarity. It has more than ten million installs, an average rating of 4.5 from roughly two hundred thirty-eight thousand ratings, and around four thousand written reviews. Those figures suggest that many people use it successfully, but they should not replace checking whether its workflow fits my own situation. Popularity cannot guarantee that a specific recipient, device, or funding method will behave exactly as expected.
Who will benefit most from it
I see Skrill working best for people who regularly need a dedicated digital payment wallet, already know that their recipient or service accepts it, and are comfortable checking transaction details before confirming. It can also suit someone who wants to separate certain online payments from their everyday bank activity. The free price makes trying it accessible, while the Everyone age rating keeps the presentation broadly approachable.
A realistic example would be splitting the cost of a shared online service with a friend who already uses Skrill. I would agree on the amount and recipient details first, open the wallet, review the final information, confirm the transfer, and wait for both sides to see the completed result. If the transaction were for an urgent household bill or a recipient who needed a conventional bank deposit, I would compare the bank’s own transfer option before choosing Skrill.
I would skip it when I need a full banking replacement, when the recipient cannot use the service, or when I am unwilling to deal with account checks and transaction-status decisions. Someone who makes only occasional card purchases may find a wallet adds complexity rather than removing it. Likewise, anyone who needs an immediate, guaranteed route for a critical payment should use the method that the recipient and their institution already handle reliably.
My practical verdict after using it
Skrill - Fast, secure payments is a capable finance app with a clear place in the digital wallet category. I like its phone-first approach and the fact that it can provide an alternative to sending every payment directly through a bank or card. The experience is strongest when I prepare the account properly, confirm that the other side accepts Skrill, and treat the final transaction status as more important than the speed of tapping through the screens.
Its main weakness is not that the idea is difficult; it is that payment workflows become unforgiving when details are wrong or a transaction does not finish cleanly. New users may need patience during setup, and experienced users still need to check fees, recipient information, funding status, and confirmation screens. That is normal for a finance service, but it means Skrill rewards careful use more than impulsive use.
With Paysafe Holdings UK Limited as its developer, a long presence since 2014, and broad adoption, it is a reasonable app to consider rather than an obscure experiment. I would install it for a specific payment need, begin with a low-risk test, and keep my normal bank or card option available. My recommendation is simple: use Skrill when its wallet workflow matches the recipient and payment, but choose a more direct method when it does not.
Pros
- Supports international transfers in multiple currencies.
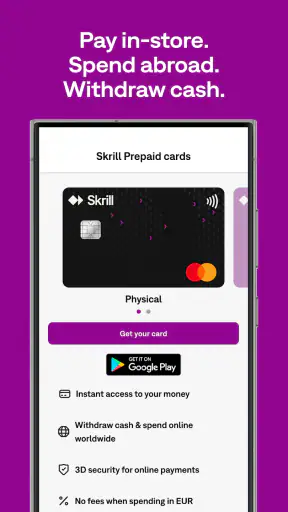
- Offers virtual and physical card options in supported regions.
- Two-factor authentication adds an extra layer of account security.
- Useful transaction notifications help track account activity.
- Available on both Android and iOS devices.
Cons
- Exchange rates may include a markup on currency conversions.
- Some withdrawals and transfers can take several business days.
- Account verification may require detailed personal documents.
- Fees vary depending on the payment method and destination.
- Certain features and cards are unavailable in some countries.
FAQs for Skrill - Fast, secure payments
What is Skrill and what can I use it for?
Skrill is a digital wallet and online payment service that lets you send and receive money, pay participating merchants, and manage funds through a mobile app or website. Depending on your country, you may also be able to use Skrill for international transfers, online purchases, prepaid services, or supported entertainment platforms. Available features can vary by region and account type.
Is Skrill safe to use for online payments and money transfers?
Skrill uses account security measures such as password protection, identity verification, transaction monitoring, and additional verification options where available. However, no payment service is completely risk-free. You should use a strong, unique password, enable available security features, avoid sharing verification codes, and only sign in through the official app or website. Always review recipient details before confirming a transaction.
Does Skrill charge fees for deposits, withdrawals, or transfers?
Skrill may apply fees depending on the transaction type, your location, currency, payment method, and account activity. Charges can apply to certain deposits, withdrawals, currency conversions, card-related services, or transfers. The exact costs may change, so check the fee information shown in the app before completing a transaction. Also remember that your bank or card provider may apply separate charges.
How long do Skrill transfers and withdrawals take?
The processing time depends on the payment method, destination, currency, verification status, and whether the transaction requires additional security checks. Transfers between Skrill users may be quick, while withdrawals to a bank account or card can take longer. Weekends, public holidays, incorrect account details, and compliance reviews may cause delays. Skrill normally displays an estimated processing time before confirmation.
What documents or verification does Skrill require?
Skrill may ask you to verify your identity before allowing certain features, higher transaction limits, withdrawals, or continued account access. Verification can include a government-issued identification document, proof of address, or information about your payment activity. Requirements differ by country and individual account. Submit documents only through the official Skrill app or website, and ensure the information matches your account details.

Skrill - Fast, secure payments
This site provides independent information about third-party apps and is not affiliated with, or the owner, developer, or distributor of, any app featured here. App names, logos, and trademarks belong to their respective owners. Developer details are provided for reference; please contact the developer directly via help@skrill.com, visit https://www.skrill.com, or review their https://www.paysafe.com/en/paysafegroup/comprehensive-privacy-notice/.










